How to Improve Cash Flow Management
Why profitable businesses still run short on cash
Profitability does not guarantee liquidity. Businesses can report profits while cash is trapped in overdue receivables or tied up in poorly timed outgoing payments.
Without a routine cash monitoring process, teams react to shortages late. Emergency borrowing, rushed collections, and delayed supplier payments then become frequent operational habits.
Cash decisions based on stale spreadsheets miss rapid shifts in collections and disbursements, especially during seasonal or high-growth periods.
Why this happens
- Cash book is not reviewed frequently enough.
- AR aging follow-up lacks urgency and ownership.
- Payable schedules are disconnected from real inflow timing.
- Cash flow reporting is treated as month-end paperwork only.
Biznsbook addresses this through cash book, cash flow statement, AR aging when Accounting is enabled; add Finance Management, Taxation, Expense, Sales, or Purchase modules as your operating model requires.
Finance teams lose days each month reconciling versions that should never have diverged. Naming Biznsbook screens as the system of record — and closing periods when agreed — prevents silent edits that auditors flag immediately.
Step-by-step: Improve Cash Flow Management
Designed for owners, bookkeepers, and controllers who need repeatable month-end discipline. Adapt roles to team size — separation of duties matters more than headcount.
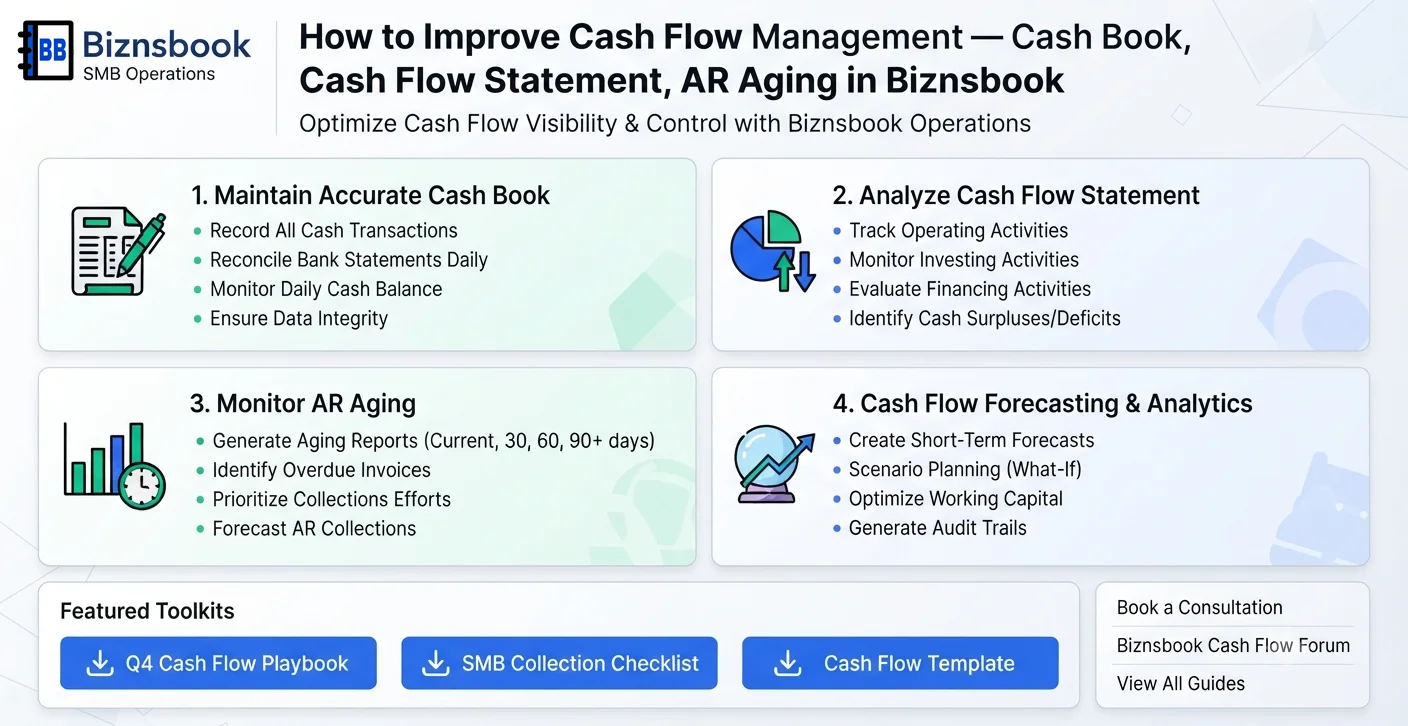
- Create a cash review cadence. Set daily and weekly routines for cash position checks with clear owner accountability.
- Monitor the cash book daily. In Biznsbook, review cash and bank movements to identify unusual outflows and delayed inflows immediately.
- Prioritize receivable collections. Use AR aging to target overdue accounts that have the largest impact on near-term liquidity.
- Use cash flow statements for patterns. Analyze Biznsbook cash flow statement trends to understand recurring operational pressure points.
- Sequence payables strategically. Align payment batches to supplier criticality, discounts, and expected collections.
- Coordinate with sales and procurement. Use Biznsbook-linked views to align invoice timing, receipts, and purchase commitments across teams.
- Track forecast accuracy. Compare projected and actual cash movement every period and adjust assumptions based on outcomes.
Review results after the first full monthly cycle. Adjust roles, mappings, or approvals where the same exception repeats.
Screen-level flows live in the Help Center. This guide focuses on the business process; help articles cover click-by-click navigation.
Common mistakes to avoid
- Mistake 1: Cash book is not reviewed frequently enough. Repeating this each month usually shows up first in trial balance or AR/AP aging.
- Mistake 2: AR aging follow-up lacks urgency and ownership. Repeating this each month usually shows up first in trial balance or AR/AP aging.
- Mistake 3: Payable schedules are disconnected from real inflow timing. Repeating this each month usually shows up first in trial balance or AR/AP aging.
- Mistake 4: Cash flow reporting is treated as month-end paperwork only. Repeating this each month usually shows up first in trial balance or AR/AP aging.
Track recurring exceptions in month-end notes; each should map to a control above.
Best practices that hold up as you scale
- Create a cash review cadence — Set daily and weekly routines for cash position checks with clear owner accountability.
- Monitor the cash book daily — In Biznsbook, review cash and bank movements to identify unusual outflows and delayed inflows immediately.
- Prioritize receivable collections — Use AR aging to target overdue accounts that have the largest impact on near-term liquidity.
- Use cash flow statements for patterns — Analyze Biznsbook cash flow statement trends to understand recurring operational pressure points.
- Sequence payables strategically — Align payment batches to supplier criticality, discounts, and expected collections.
Consistency beats heroics at month-end. A smaller team that closes the same calendar every month outperforms a larger team that posts sporadically.
How Biznsbook supports this workflow
cash book is documented in Biznsbook Accounting / Finance capabilities. Use it as part of a controlled finance process — posting, review, and period close — not as an isolated export. When Sales, Purchase, Inventory, Taxation, Expense, or Finance Management modules are enabled, related documents can post through the central accounting posting service with double-entry validation.
cash flow statement is documented in Biznsbook Accounting / Finance capabilities. Use it as part of a controlled finance process — posting, review, and period close — not as an isolated export. When Sales, Purchase, Inventory, Taxation, Expense, or Finance Management modules are enabled, related documents can post through the central accounting posting service with double-entry validation.
AR aging is documented in Biznsbook Accounting / Finance capabilities. Use it as part of a controlled finance process — posting, review, and period close — not as an isolated export. When Sales, Purchase, Inventory, Taxation, Expense, or Finance Management modules are enabled, related documents can post through the central accounting posting service with double-entry validation.
Permissions are role-based: separate chart maintenance, journal creation, report viewing, period close, and bank reconciliation per tenant policy.
Suggested implementation timeline
- Week 1: Document current process gaps and configure cash book with finance owner sign-off.
- Weeks 2–3: Pilot on one month or one entity; post all test transactions through Biznsbook; freeze parallel spreadsheet journals.
- Week 4: Run first trial balance or report tie-out; fix mapping and permission issues.
- Month 2–3: Roll out to full team; add approvals and period close cadence from this guide.
- Ongoing: Monthly review using cash war-room metrics and leadership dashboard.
Metrics to track monthly
- Days to complete month-end close
- Unreconciled bank lines outstanding
- AR and AP aging buckets over 30/60/90 days
- Trial balance out-of-balance exceptions
- Manual journal count vs automated postings ratio
Start with three metrics; trend direction matters more than a single point-in-time snapshot.
Spreadsheet / manual books vs integrated ERP
Compare typical manual finance work with Biznsbook cash book and related capabilities.
| Capability | Manual / Spreadsheet | Biznsbook |
|---|---|---|
| Cash visibility | ❌ Periodic spreadsheet snapshots | ✅ Daily cash book insight |
| Inflow control | ❌ Reactive collection calls | ✅ AR aging-driven prioritization |
| Outflow timing | ❌ Unplanned payment decisions | ✅ Structured payable scheduling |
| Trend analysis | ❌ End-month guesswork | ✅ Cash flow statement patterns |
| Cross-team planning | ❌ Department silos | ✅ Shared finance-operational view |
| Forecast confidence | ❌ Low predictability | ✅ Regular projected vs actual review |
Cash war-room metrics
Track opening cash, expected collections, mandatory outflows, discretionary spend, and overdue AR concentration. These five metrics provide a practical short-term liquidity control panel.
Document this in your finance SOP and revisit each quarter as transaction volume or entity structure changes.
Frequently asked questions
How often should cash position be reviewed?
Daily for active businesses, with deeper weekly analysis. Frequent review reduces surprise shortages and supports better payment timing decisions.
What report helps most with short-term planning?
Cash book is best for immediate visibility, while cash flow statement helps identify recurring structural trends.
How does AR aging support liquidity?
It highlights overdue invoices by severity, helping teams focus collection effort where cash recovery impact is highest.
Can cash flow improve without revenue growth?
Yes. Better collection timing, disciplined payable scheduling, and tighter expense control can materially improve liquidity.
How this differs by industry
Retail
Retail operators can stabilize liquidity by tracking card settlement timing, daily cash movements, and overdue trade receivables in one rhythm.
Wholesale & distribution
Wholesale distributors improve cash resilience when high-value AR follow-up is linked to deliberate supplier payment sequencing.
Manufacturing
Manufacturers can reduce cash strain by aligning raw-material payments with realistic collection cycles and production billing milestones.